Your Annuity Guaranteed Withdrawal Fee Outlasts the Income It Promised
A guaranteed lifetime withdrawal benefit (GLWB) rider on a variable annuity is marketed as a safety net that allows you to withdraw a fixed percentage of your benefit base every year for life, regardless of market performance. The catch, buried in the prospectus, is that the net continues to collect a fee long after the safety net has frayed.
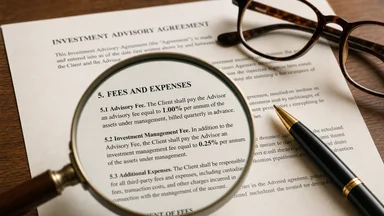
The typical GLWB rider charges an annual fee in the range of 0.95% to 1.25% of the account value. The fee is deducted quarterly from the cash value, not from the benefit base. When markets fall and withdrawals continue, the cash value can drop to zero while the benefit base remains positive—and the fee keeps coming. The insurer continues to collect its percentage of an account value that is, for all practical purposes, gone. The income the rider promised may still be paid, but the cost of that promise has outlived the principal that was supposed to fund it.
This is not a fringe product. According to industry data cited in regulatory filings, roughly 60% of variable annuity contracts sold in recent years include some form of living benefit rider, with GLWB being the most common. The total assets under these riders run into the hundreds of billions. Yet the fee structure, the tax treatment, and the break-even math are rarely explained to buyers in plain language. This article walks through each layer: where the fee goes, what it does to your net income, how taxes compound the drag, and whether cheaper alternatives can deliver a similar outcome.
The Sales Pitch vs. The Payout Math
Consider a typical scenario. You invest a lump sum—say $200,000—into a variable annuity with a GLWB rider. The rider establishes a benefit base, often equal to the initial premium, that grows by a guaranteed percentage (typically 5% to 7% per year for a deferral period) and is used to calculate your lifetime withdrawal amount. You can withdraw, for example, 5% of that benefit base each year, even if the underlying investments lose value. The promise: you will never outlive your income.
The math behind the pitch is less comforting. That 1% annual rider fee is deducted from the cash value, not the benefit base. If the cash value declines due to market losses or withdrawals, the fee as a percentage of what remains can become much larger. Consider a $200,000 account with a 1% annual fee and a 5% withdrawal rate. In the first year, the fee is $2,000 and the withdrawal is $10,000. If the portfolio loses 10% in year one, the cash value drops to roughly $170,000 after fees and withdrawals. The fee in year two is 1% of $170,000, or $1,700—still a meaningful drag on a shrinking base.
Over time, the fee consumes a growing share of the annual withdrawal. In a flat or negative market, the fee can represent 15% to 25% of the gross withdrawal amount. The rider that was supposed to protect your income is, in effect, taking a cut of every check. The insurance company is not sharing in the downside; it is collecting a steady stream of fees regardless of performance. This asymmetry is the central contradiction of the product: the guarantee is priced as though the insurer bears risk, but the fee structure ensures the insurer is paid first.
Proponents argue that the rider provides peace of mind and that the fee is reasonable compared to the cost of a standalone longevity annuity. But peace of mind has a price, and that price is compounded annually. A buyer who lives to age 90 and began withdrawals at 65 will have paid fees for 25 years—including years when the cash value was zero and the benefit base was the only thing keeping the income alive. The total fees paid can easily exceed 30% of the initial premium.
Where the Fee Goes — and Who Keeps It
The GLWB rider fee is not a single line item on a statement. It is embedded in the annuity contract as a separate charge, typically deducted pro rata from the cash value each quarter. The fee compensates the insurer for the guarantee that the benefit base will be available for lifetime withdrawals, but the mechanics of how it is collected matter enormously for the net return.
Because the fee is deducted from cash value, it reduces the pool of assets available for investment growth. In a rising market, this drag is partially masked by gains. In a falling or flat market, the fee accelerates the depletion of the cash value. The benefit base, meanwhile, continues to grow at its contractual rate (often 5% to 7% during the deferral period), creating a widening gap between the notional benefit base and the actual account value. This gap is the source of the insurer's profit: the insurer is betting that the cash value will not support the full withdrawal stream, and that many policyholders will surrender or die before collecting the full benefit.
The fee also covers the cost of hedging the guarantee. Insurers typically hedge their GLWB exposure using derivatives such as equity and interest rate swaps. These hedging costs are passed through to the rider fee. But the efficiency of the hedge matters. If the insurer over-hedges or uses expensive instruments, the fee may be higher than necessary. State insurance regulators review these charges, but the fee is ultimately a matter of contract pricing, not a regulated utility rate.
Commissions on variable annuities with riders can be substantial—often 5% to 7% of the premium, paid upfront by the insurer from the fee stream. This creates a misalignment: the advisor is compensated at the point of sale, while the fee burden falls on the policyholder for decades. The buyer may not see the ongoing cost as a direct drain because it is deducted before the account value is reported, but it is real and material.
The Haircut That Keeps Cutting
The term "haircut" in finance usually refers to the discount applied to collateral when calculating loan value. In the annuity context, the rider fee acts as a haircut on your principal—a persistent reduction that compounds over time. Unlike a one-time haircut on a bond posted as collateral, the annuity rider haircut is applied year after year, regardless of market conditions.
To see the effect, consider a simple withdrawal strategy without a rider. You invest $200,000 in a portfolio of 60% stocks and 40% bonds, and you withdraw 5% annually. Over 30 years, assuming a 7% gross return and 0.10% fund fees, the portfolio would sustain withdrawals for roughly 25 years before depletion, depending on sequence of returns. With a GLWB rider charging 1% annually, the net return drops to 6% before the rider fee, and the fee itself reduces the effective withdrawal amount. The rider does not prevent depletion; it merely shifts the timing and guarantees that if you live beyond the depletion point, the insurer will continue paying—but at a reduced net income due to the fee.
The haircut is especially severe in the early years of retirement, when the portfolio is largest and the fee is highest in dollar terms. A $200,000 account with a 1% fee loses $2,000 per year, or roughly 20% of a $10,000 annual withdrawal. That $2,000 could have been left in the portfolio to grow. Over ten years, the foregone growth on those fees, compounded at 6%, amounts to roughly $26,000—more than a full year of withdrawals.
Some advisors counter that the rider fee is worth it because the guarantee protects against sequence-of-returns risk. If the market drops 30% in the first year of retirement, a GLWB rider ensures the benefit base does not fall, so the withdrawal amount stays constant. But the fee still applies, and the cash value drop means the fee is deducted from a smaller base, increasing its proportional impact. The rider does not eliminate the cost of a bad start; it merely caps the downside of the benefit base while the cash value takes the hit.
Tax Timing: The Deferred Trap
Annuities are tax-deferred vehicles. Earnings grow without current taxation, but withdrawals are taxed as ordinary income. The GLWB rider fee, however, is not deductible. It is paid with after-tax dollars—or, more precisely, it reduces the cash value, which is itself pre-tax money inside a qualified account. The net effect is that the fee reduces the amount available for future withdrawals, and those future withdrawals will be fully taxed at ordinary income rates.
Inside a qualified account such as an IRA or 401(k), the entire withdrawal—including the portion that represents return of premium—is taxed as ordinary income. The rider fee, by reducing the cash value, effectively increases the proportion of each withdrawal that is considered taxable earnings. This is a subtle but real tax cost: the fee accelerates the recognition of taxable income relative to a non-annuity investment.
For non-qualified annuities (purchased with after-tax dollars), the tax treatment is different. Withdrawals are treated as coming first from earnings (LIFO), so early withdrawals are fully taxable. The rider fee, deducted from cash value, reduces the basis but does not change the LIFO ordering. Over time, the fee reduces the net after-tax return. A policyholder who surrenders the contract early may face a surrender charge plus tax on the earnings, and the rider fee has already consumed a portion of the account that could have been withdrawn tax-free as return of basis.
The lack of a step-up in basis at death is another hidden cost. With a taxable brokerage account, heirs receive a step-up in basis to the date-of-death value, eliminating capital gains tax on appreciation. An annuity does not receive a step-up; the beneficiary must pay ordinary income tax on the earnings. The rider fee, by reducing the account value, reduces the amount that passes to heirs, but the tax liability on the remaining earnings is unchanged. The guarantee that seemed valuable during retirement becomes a drag on the estate.
When the Guarantee Breaks Even
The break-even point for a GLWB rider depends on how long you live, how the market performs, and the timing of withdrawals. Studies by actuarial firms suggest that the probability of collecting more in lifetime withdrawals than you would have received from a comparable systematic withdrawal plan is roughly 30% under moderate assumptions. That means 70% of policyholders would have been better off without the rider, even accounting for the peace of mind.
Breakeven typically requires living past age 85 to 90, depending on the withdrawal rate and fee structure. If you die at 80, you have paid fees for 15 years without ever needing the guarantee. The insurer keeps the fees and the remaining cash value. The rider is, in effect, a longevity insurance policy that only pays off if you live longer than average—and even then, the net benefit is reduced by the cumulative fees.
Sequence-of-returns risk cuts both ways. If the market drops early and recovers later, the rider can be valuable because the benefit base does not drop. But if the market rises early, the rider locks in a lower benefit base growth than the actual portfolio might have achieved. The fee is a constant drag regardless of the market path. Some studies show that a GLWB rider adds value only in the worst 10% to 20% of market scenarios—precisely the scenarios that are hardest to predict.
Insurers profit from the fact that many policyholders surrender or die early. Lapse rates on variable annuities are high; a 2019 study by the Society of Actuaries found that roughly 30% of contracts lapse within 10 years. Those lapsers pay fees without ever receiving a guaranteed withdrawal. The rider fee structure is designed to collect from the many to pay the few who live long and see poor markets.
Cheaper Alternatives That Mimic the Promise
A systematic withdrawal plan from a low-cost portfolio of index funds can replicate the income stream of a GLWB rider at a fraction of the cost. Total fund expenses of 0.03% to 0.10% replace the 1% rider fee. The portfolio can be rebalanced and adjusted for inflation. The risk, of course, is that the portfolio may be depleted if the retiree lives long or markets perform poorly. But that risk can be managed.
A TIPS ladder provides an inflation-protected income floor. By purchasing Treasury Inflation-Protected Securities that mature in each year of retirement, you can create a stream of real income with essentially zero credit risk and no ongoing fee beyond the minimal expense of a fund or direct purchase. The cost is the foregone yield relative to nominal bonds, which historically has been small.
A single-premium immediate annuity (SPIA) offers a lifetime income guarantee with no ongoing rider fee. The premium is paid upfront, and the insurer calculates the payout based on your age and interest rates. The trade-off is that the money is irrevocably committed—no liquidity, no death benefit. But the cost is transparent: a one-time premium, not a recurring fee that outlasts the account value.
Combining a SPIA with a systematic withdrawal plan can create a floor-and-upside strategy. The SPIA covers essential expenses; the portfolio covers discretionary spending. Total fees are lower, and the retiree retains control over the portfolio. For those who want a guarantee but dislike the GLWB fee structure, this hybrid approach is worth examining. Some financial advisors call it the "two-bucket" method, and it has been discussed in outlets like the Journal of Financial Planning (see, for example, the article "Using a Two-Bucket Strategy to Manage Retirement Income").
The Revision: Don't Buy the Income, Buy the Time
The GLWB rider fee is a bet on your own longevity. You are paying the insurer to take the risk that you will live long enough to exhaust your account. That is a reasonable bet for some, but the pricing is opaque and the fee structure is punitive for those who die early or surrender. The insurance company is not your partner; it is your counterparty, and it has designed the fee to be collected for as long as possible.
If you decide that a lifetime income guarantee is worth the cost, consider a deferred income annuity (also called a longevity annuity) instead of a GLWB rider. A deferred income annuity is purchased at retirement with a lump sum, and payments begin at a specified future age—say 80 or 85. There are no ongoing fees after the premium is paid. The guarantee is explicit: you pay now, and the insurer promises to pay later. The cost is a single premium, not a recurring charge that eats into your portfolio.
For those who already own a GLWB rider, the decision to surrender is complex. Surrender charges and tax consequences may outweigh the benefit of eliminating the fee. A careful net-present-value analysis under realistic return assumptions is warranted. The fee may be small relative to the total portfolio, but over a 30-year retirement, it can amount to tens of thousands of dollars. Every dollar paid in fees is a dollar that cannot be spent or invested.
Living-benefit riders on tax-deferred accounts combine ongoing fees, ordinary income tax, and no step-up in basis—a triple tax drag that is hard to overcome. For a taxable account, the case is slightly better because of the potential for capital gains treatment, but the fee still erodes returns. Before adding a rider, run the numbers with a realistic fee schedule and a range of market scenarios. The guarantee may be worth it, but the fee should not outlast the income it promised. Ultimately, the decision hinges on individual longevity expectations, risk tolerance, and the availability of lower-cost alternatives. No single product fits all retirees, and the GLWB rider is best evaluated as one option among many, not as a default solution.
Disclaimer: This article is for informational and educational purposes only and does not constitute personalized financial or tax advice. Consult a qualified professional before making decisions about annuity products or retirement withdrawal strategies.