One Annuity Prospectus Paragraph That Charges Fees on Fees You Never Authorized
Somewhere in the 150-plus pages of your variable annuity prospectus, there is a paragraph that quietly authorizes a fee on a fee. It does not say that in bold type. It uses phrases like “mortality and expense risk charge” and “rider charge as a percentage of the benefit base.” The math is buried. The dollar impact is not shown. By the time you realize what happened, the insurance company has collected a second layer of fees on money you never authorized them to charge fees on.
This article follows the money. It identifies the paragraph, shows how the fee-on-fee compounds, names the intermediaries who collect, and explains the tax treatment that makes withdrawals even costlier. The goal is not to condemn all annuities—some fixed immediate annuities serve a purpose—but to expose a disclosure gap that costs retirees tens of thousands of dollars.
The Paragraph That Hides a Second Fee Layer
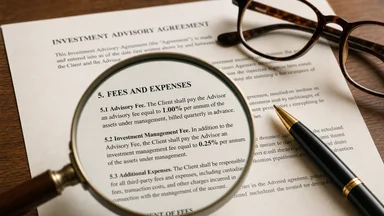
The paragraph in question is typically labeled “Mortality and Expense Risk Charge” (M&E). It appears in the fee table of every variable annuity prospectus. The M&E charge covers the insurance company’s risk that you live longer than expected (mortality) and that its expenses exceed projections (expense). In practice, it is a flat percentage of your account value, usually between 1.25% and 1.50% annually. That alone is significant—a $100,000 account pays $1,250 to $1,500 per year regardless of performance.
But the M&E charge is only the first layer. Many variable annuities are sold with optional riders, such as a guaranteed lifetime withdrawal benefit (GLWB) or a guaranteed minimum income benefit (GMIB). These riders add a separate fee, typically 0.95% to 1.10% of the “benefit base” each year. The benefit base is often defined as the highest anniversary value of the account, or the initial premium plus credits, not the current market value. That means the rider fee is calculated on a number that can be larger than the account value—and it is applied on top of the M&E charge.
Here is where the fee-on-fee occurs. The rider fee is expressed as a percentage of the benefit base, but the benefit base itself grows with premiums and sometimes with a guaranteed roll-up rate. The M&E charge is deducted from the account value. The rider fee is deducted from the account value as well. So the insurance company first subtracts the M&E charge (say 1.35% of the account), then subtracts the rider fee (say 1.00% of the benefit base, which may be larger than the account). The total annual fee can reach 2.5% to 3.5% of the account value. The rider fee is effectively a fee on the portion of the account that already paid the M&E charge. There is no line item that says “fee on fee.” The prospectus simply lists them as separate percentages.
Why the Prospectus Language Is Designed to Confuse
The average variable annuity prospectus runs over 150 pages. The fee table appears early, but it uses annual percentages, not dollar examples. A reader sees “Mortality and Expense Risk Charge: 1.35%” and “Rider Fee: 1.00%.” Without a calculator, the combined 2.35% seems abstract. The prospectus does not show a column for “total fees in dollars over 10 years.” The SEC requires clear disclosure of fees, but it does not require a simplified math illustration that adds the percentages together and projects the cumulative cost. That gap is by design—or at least by omission.
Annuity buyers are often older individuals making a financial decision under time pressure from an advisor. The average buyer spends less than 30 minutes reviewing the prospectus, according to industry surveys. The fee table is dense, filled with footnotes that define terms like “benefit base” and “guaranteed minimum withdrawal amount.” The paragraph that describes how the rider fee is calculated—often on a benefit base that may exceed the account value—is buried on page 47 or 62. No summary page highlights the fee-on-fee effect.
Industry defenders argue that the disclosure meets regulatory standards and that buyers can request a personalized illustration. But a personalized illustration is rarely offered proactively. An investor who asks for “a projection of fees in dollars assuming a 6% return” may get a document that shows gross returns and net returns, but often omits the compounding effect of fees on fees. The language is technically accurate but practically misleading. As one former SEC attorney told me, “The rules require disclosure of the fee structure, not a warning that the structure imposes a hidden double charge.”
Consider a real-world example from a major insurer. A prospectus for a popular variable annuity from a well-known company lists the M&E charge as 1.35% and the GLWB rider fee as 1.05% of the benefit base. The benefit base is defined as the greater of the initial premium or the highest contract anniversary value. In a year when the account value drops to $90,000 due to market losses, but the benefit base remains at $100,000 (the initial premium), the rider fee of 1.05% is applied to $100,000—yielding a $1,050 charge—while the M&E charge of 1.35% is applied to the actual $90,000 account value, yielding $1,215. The total fee that year is $2,265 on an account worth $90,000, an effective rate of 2.52% on the account value. That is the fee-on-fee in action: a charge on a base that no longer exists.
The Real Cost: How Compounding Fees Eat Returns
Consider a $100,000 variable annuity with a GLWB rider. Assume the M&E charge is 1.35%, the rider fee is 1.00%, and the underlying fund expenses average 0.50%. That is a total annual expense of 2.85%. If the gross return is 6% per year, the net return after fees is 3.15%. Over 20 years, $100,000 growing at 6% gross becomes approximately $320,714. After fees, it grows to about $185,000. The difference—roughly $135,000—is consumed by fees. That is 42% of the gross growth. By comparison, a low-cost index fund with a total expense ratio of 0.10% would grow the same $100,000 to about $308,000, keeping 96% of the growth.
The compounding effect is brutal. In year one, fees total $2,850 on a $100,000 account. By year ten, if the account has grown to $135,000 (net), fees are about $3,850. By year twenty, fees exceed $5,200 annually. The fee-on-fee structure accelerates this because the rider fee is often calculated on a benefit base that grows by a guaranteed roll-up rate (say 5% per year) regardless of market performance. In a down market, the benefit base may be higher than the account value, meaning the rider fee is a larger percentage of the actual cash value. That is the second layer: the fee base is disconnected from the asset base.
Surrender penalties add another layer of cost. Most variable annuities have a surrender charge schedule that starts at 7% to 10% of the account value and declines over 6 to 10 years. If you need to withdraw more than the free amount (usually 10% per year), you pay a penalty on the excess. That penalty is calculated on the amount withdrawn, not the original premium. So if you surrender $50,000 in year three, you might pay $3,500 to $5,000 in penalties—on top of the fees already deducted. The combination of M&E, rider, fund expenses, and surrender charges can push the first-year cost to 10% or more of the initial investment.
To illustrate the compounding effect more concretely, consider a scenario with a market downturn. Suppose in year three the account value drops to $80,000 while the benefit base remains at $100,000 due to a roll-up. The M&E charge (1.35%) is $1,080, the rider fee (1.00% of $100,000) is $1,000, and fund expenses (0.50% of $80,000) are $400. Total fees: $2,480 on an $80,000 account—an effective rate of 3.10%. Meanwhile, the gross return that year might be negative, so the net loss is even larger. The rider fee, which is supposed to protect you in down markets, actually exacerbates the loss because it is calculated on a base that does not shrink. This counter-intuitive feature is rarely explained in sales materials.
Who Collects: The Intermediary Chain
The insurance company retains the M&E charge. This is pure revenue that covers the insurer’s risk and profit. For a typical variable annuity, the M&E charge of 1.25% to 1.50% generates a steady stream of income. The insurer also earns revenue from the rider fee, which may be partially ceded to a reinsurer. The rider fee is priced based on actuarial assumptions, but the actual cost of providing the guarantee is opaque. Some estimates suggest that the rider fee exceeds the cost of the guarantee by a wide margin, especially in rising interest rate environments.
The broker-dealer receives an upfront commission, typically 7% to 10% of the premium. On a $100,000 annuity, that is $7,000 to $10,000 paid by the insurance company out of the premium. That commission is not deducted transparently; it is built into the product’s cost structure. The financial advisor who sold the annuity receives a trailing commission, usually 0.25% to 1.00% of the account value annually. This creates a conflict of interest: the advisor has an incentive to keep you in the annuity year after year, even if a lower-cost alternative would serve you better.
No single party in the chain bears a fiduciary duty to you. The insurance company owes a contractual duty, not a fiduciary one. The broker-dealer must recommend suitable products but not necessarily the cheapest. The advisor may be held to a best-interest standard under Regulation Best Interest, but that standard does not require disclosure of the fee-on-fee structure or a comparison to low-cost alternatives. The result is a system where each intermediary collects a piece, and the cumulative cost is not visible to the buyer.
To understand the full economics, consider a simplified example. On a $100,000 annuity with a 7% upfront commission, the broker-dealer receives $7,000. The advisor gets a 0.50% trailing commission, or $500 in the first year. The insurance company collects the M&E charge ($1,350) and rider fee ($1,000) for a total of $2,350. After paying the commissions and administrative costs, the insurer’s profit margin is estimated to be around 20–30% of the fees collected. The remaining fees cover the cost of guarantees, which may be as low as 0.20% to 0.40% of the benefit base according to some actuarial studies. This implies that the rider fee is significantly padded to cover commissions and profits.
Tax Treatment: The Second Tax on Withdrawals
Annuities offer tax deferral, but the tax treatment on withdrawals is punitive. Earnings are withdrawn first on a last-in, first-out (LIFO) basis, meaning every withdrawal is taxed as ordinary income until all earnings are exhausted. If you have a $100,000 annuity with $30,000 in earnings, the first $30,000 you withdraw is fully taxable at your marginal rate, which could be 22% to 37% for most retirees. By contrast, a taxable brokerage account allows you to sell shares with specific identification, minimizing capital gains. An annuity offers no such flexibility.
There is no step-up in basis at death. If you hold stocks in a taxable account, your heirs receive a step-up in basis to the date-of-death value, eliminating capital gains tax. With an annuity, your heirs pay ordinary income tax on the entire earnings portion. If the annuity has grown to $200,000 with $100,000 in earnings, your heirs owe tax on that $100,000 at their ordinary rate. That can be a 25% to 40% tax hit, depending on their income. The tax deferral is merely a delay, not a savings.
A 1035 exchange allows you to transfer an annuity to another annuity without triggering tax, but it resets the surrender charge clock. Many investors use 1035 exchanges to move from one high-fee annuity to another, never escaping the fee structure. Required minimum distributions (RMDs) apply to annuities held in qualified retirement accounts starting at age 73. If the market is down when you must withdraw, you lock in losses and pay tax on the withdrawal. State tax treatment varies: some states exempt a portion of annuity income from state tax, but others tax it fully. The tax complexity adds another layer of cost that is rarely disclosed in the prospectus.
For example, a retiree in a state with a 5% income tax who withdraws $20,000 from a non-qualified annuity might owe $4,400 in federal tax (22% bracket) and $1,000 in state tax, leaving only $14,600 net. If the same $20,000 came from a brokerage account with long-term capital gains, the federal tax might be only $3,000 (15% rate) and state tax $1,000, netting $16,000. The annuity withdrawal costs $1,400 more in taxes. Over many years of withdrawals, this tax penalty can add up to tens of thousands of dollars.
A Better Way: What Fee-Aware Investors Do Instead
For most investors, a self-directed IRA with low-cost ETFs or index funds offers better outcomes. The total expense ratio can be as low as 0.03% to 0.15% annually. There are no M&E charges, no rider fees, and no surrender penalties. You control the asset allocation and can rebalance tax-free within the IRA. The only downside is that you bear the investment risk—there is no guarantee of lifetime income. But for the typical retiree who can manage a systematic withdrawal plan, the cost savings dwarf the value of the guarantee.
A fixed immediate annuity can serve as a partial income floor. In a fixed immediate annuity, you pay a lump sum and receive a guaranteed monthly payment for life. The fee structure is simpler: the insurance company keeps the spread between the payout rate and its investment return. There are no separate M&E or rider fees. The cost is embedded in the payout rate. For someone who needs a base of guaranteed income, a fixed immediate annuity can be a reasonable choice—but only for a portion of savings.
Another alternative is a fee-only financial advisor who charges a flat fee or hourly rate rather than commissions. Such an advisor can help you build a diversified portfolio of low-cost funds and implement a systematic withdrawal strategy that mimics the income stream of an annuity without the high fees. For those who want a guaranteed lifetime income, a longevity annuity (a deferred income annuity) purchased at age 70 or later can provide a cost-effective way to insure against outliving your assets, with lower fees than a variable annuity.
Before signing any annuity contract, ask for a fee-in-dollars illustration. Request a projection that shows the total dollar amount of fees deducted each year for 20 years, assuming a 6% gross return. Compare that to a low-cost alternative. Compare the total expense ratio across providers. Vanguard’s variable annuity, for example, has an M&E charge of 0.45%, far lower than the industry average of 1.35%. Lincoln Financial and Jackson National often charge higher fees but offer more aggressive riders. The difference of 0.90% per year can amount to tens of thousands of dollars over two decades. Know the numbers before you sign.
Finally, consider the counter-argument: some investors value the behavioral benefits of a guaranteed income stream. The peace of mind from knowing you cannot outlive your savings may be worth the cost, especially for those who lack the discipline to manage withdrawals. However, this argument only holds if the investor fully understands the fees and accepts them consciously. The problem is that the fee-on-fee structure is hidden, so the decision to pay it is not an informed one. By exposing the mechanics, this article aims to give you the information needed to make that choice deliberately.
This article is for informational purposes only and does not constitute personalized financial, legal, or tax advice. Consult a qualified professional before making any investment decisions.